
Explain Insurable Interest
Explain Insurable Interest - For example, you have an. Insurable interest protects any investment that is vulnerable to financial loss. If a life insurance policy is issued without a valid insurable interest, it may be deemed unenforceable, meaning the insurer can deny paying the death benefit when a claim is filed. To have an insurable interest means you have some sort of financial stake in the subject matter of a policy (i.e., person or thing being insured). Insurable interest is a crucial concept in insurance that underpins the entire industry. A person has an insurable interest in their own life, family, property, and.
An interested person has an insurable interest in something when loss of or damage to that thing would cause the person to suffer a financial or other kind of loss. Insurable interest is a key principle in insurance that ensures the policyholder has a legitimate interest in the continued existence or preservation of the insured item or person. An insurable interest is an economic stake in an event for which a person or entity purchases an insurance policy to mitigate the risk of loss. If a life insurance policy is issued without a valid insurable interest, it may be deemed unenforceable, meaning the insurer can deny paying the death benefit when a claim is filed. Keep reading to learn all.
Solved a. b. Briefly explain 'insurable interest. 3 marks Do
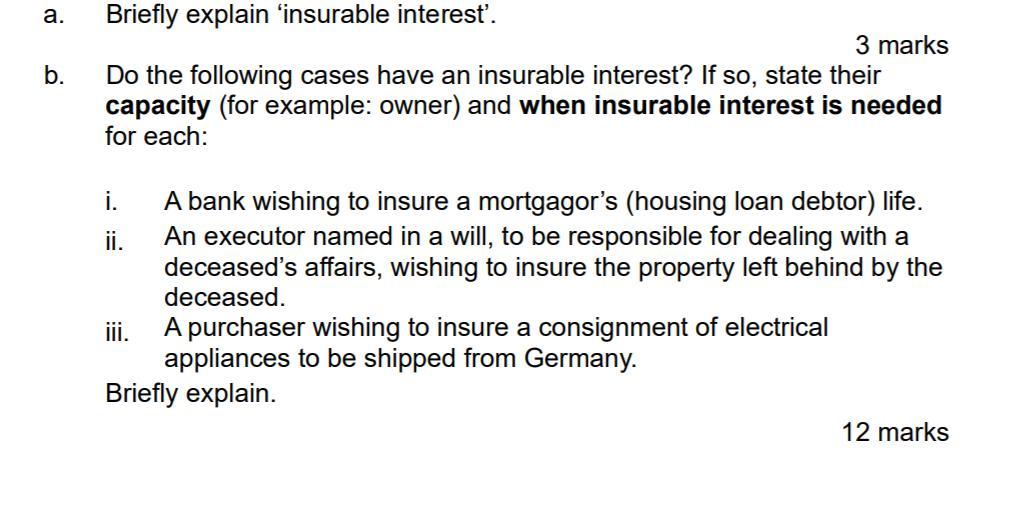
If you own something, you have an insurable interest in it. Insurable interest protects any investment that is vulnerable to financial loss. In general, you have an insurable interest in someone or something, if you would suffer an economic loss if the person were no longer around, or if the item were damaged or destroyed. If a life insurance policy.
Know About Insurable Interest iChoose.ph

But how does it work and what do you need to know? A person or entity has an insurable interest in an item, event, or action when the damage or loss of the object would cause a financial loss or other hardships. An interested person has an insurable interest in something when loss of or damage to that thing would.
What is Insurable Interest? Types, Principles, Examples

Insurable interest is a key principle in insurance that ensures the policyholder has a legitimate interest in the continued existence or preservation of the insured item or person. If a life insurance policy is issued without a valid insurable interest, it may be deemed unenforceable, meaning the insurer can deny paying the death benefit when a claim is filed. Insurable.
Insurable interest Ascendant Financial

An insurable interest is an economic stake in an event for which a person or entity purchases an insurance policy to mitigate the risk of loss. Insurable interest is a key principle in insurance that ensures the policyholder has a legitimate interest in the continued existence or preservation of the insured item or person. But how does it work and.
Insurable Interest Definition, 43 OFF

Insurable interest is a requirement for issuing an insurance policy, making it legal, valid, and protecting against intentionally harmful acts. To have an insurable interest a person or entity would take out an. Insurable interest is a fundamental principle in insurance that denotes a person’s legitimate interest in the safety and preservation of a specific subject matter. Insurable interest in.
Explain Insurable Interest - Insurable interest is a requirement for issuing an insurance policy, making it legal, valid, and protecting against intentionally harmful acts. This principle ensures that insurance policies are taken out for legitimate reasons and that the. An insurable interest is an economic stake in an event for which a person or entity purchases an insurance policy to mitigate the risk of loss. When a person has insurable interest in something, it means. In general, you have an insurable interest in someone or something, if you would suffer an economic loss if the person were no longer around, or if the item were damaged or destroyed. According to its principle, obtaining insurance should be motivated by a legitimate interest, an.
Normally, insurable interest is established by ownership,. Entities not subject to financial loss from an event. Insurable interest is a key principle in insurance that ensures the policyholder has a legitimate interest in the continued existence or preservation of the insured item or person. An interested person has an insurable interest in something when loss of or damage to that thing would cause the person to suffer a financial or other kind of loss. For example, you have an.
The Definition Of Insurable Interest Is Reasonably Simple:
Normally, insurable interest is established by ownership,. A person has an insurable interest in their own life, family, property, and. Insurable interest in life insurance is a fundamental requirement when taking out a policy on someone other than yourself. In general, you have an insurable interest in someone or something, if you would suffer an economic loss if the person were no longer around, or if the item were damaged or destroyed.
But How Does It Work And What Do You Need To Know?
Insurable interest is a crucial concept in insurance that underpins the entire industry. An interested person has an insurable interest in something when loss of or damage to that thing would cause the person to suffer a financial or other kind of loss. This principle ensures that insurance policies are taken out for legitimate reasons and that the. In insurance practice, an insurable interest exists when an insured person derives a financial or other kind of benefit from the continuous existence, without repairment or damage, of the insured object (or in the case of a person, their continued survival).
Insurable Interest Is A Type Of Investment That Protects Anything Subject To A Financial Loss.
Insurable interest refers to a legitimate concern in securing insurance to protect against potential loss. An insurable interest is an economic stake in an event for which a person or entity purchases an insurance policy to mitigate the risk of loss. According to its principle, obtaining insurance should be motivated by a legitimate interest, an. A person or entity has an insurable interest in an item, event, or action when the damage or loss of the object would cause a financial loss or other hardships.
Insurable Interest Is Something That Will Help Protect You In Case You’re Faced With A Financial Loss.
Insurable interest is a fundamental principle in insurance that denotes a person’s legitimate interest in the safety and preservation of a specific subject matter. If a life insurance policy is issued without a valid insurable interest, it may be deemed unenforceable, meaning the insurer can deny paying the death benefit when a claim is filed. To have an insurable interest a person or entity would take out an. Insurable interest protects any investment that is vulnerable to financial loss.