
Insurance Contingency That May Cause A Loss
Insurance Contingency That May Cause A Loss - The contingency is the risk of loss assumed by the insurer, that is, the risk of loss from events that may occur during the term of. Marsh’s team understands these circumstances and can help clients access innovative contingency insurance coverages, assist with manuscript policies and produce tailored. This section focuses on contingencies associated with medical malpractice claims, which are typically the most significant exposure for health care organizations. What is a contract of insurance? Contingency insurance is a type of insurance coverage designed to protect individuals or organizations against specific risks or unforeseen events that could result in financial loss or. A fundamental doctrine in property insurance hold that when there is an unbroken connection between an occurrence and damage that grows out of the occurrence, then the resultant damage is all a part of the occurrence.
What is a contract of insurance? Business interruption insurance is insurance that a reporting entity might purchase to cover losses caused by the loss of use of property or equipment. Contingency insurance serves as a critical safeguard against unforeseen events that may disrupt business operations or cause financial losses. Marsh’s team understands these circumstances and can help clients access innovative contingency insurance coverages, assist with manuscript policies and produce tailored. The contingency insurance industry is a specialized group of individuals that deal with insurance products that usually fall outside of the more easily recognized property, marine, casualty, and.
Contingency Planning Strategies for Resilience and Prepared

The contingency insurance industry is a specialized group of individuals that deal with insurance products that usually fall outside of the more easily recognized property, marine, casualty, and. Through the proliferation of contingent risk insurance, businesses and individuals can now mitigate that downside risk by preventing potential windfall losses, locking in a. A fundamental doctrine in property insurance hold that.
Legal Contingency Insurance Lost Share Certificate Indemnity Aviva

The policyholder pays a premium to the. A key factor in determining coverage is the concept of a “peril,” which refers to. Marsh’s team understands these circumstances and can help clients access innovative contingency insurance coverages, assist with manuscript policies and produce tailored. Contingency insurance is a type of insurance coverage designed to protect individuals or organizations against specific risks.
Formidable Loss Contingency Journal Entry Projected Balance Sheet

The policyholder pays a premium to the. Marsh’s team understands these circumstances and can help clients access innovative contingency insurance coverages, assist with manuscript policies and produce tailored. The major types of losses insured against through a life. Contingency insurance for business disruptions refers to specialized coverage designed to mitigate financial losses stemming from unexpected events that can negatively. Through.
Formidable Loss Contingency Journal Entry Projected Balance Sheet

Business interruption insurance is insurance that a reporting entity might purchase to cover losses caused by the loss of use of property or equipment. In the context of insurance, contingency insurance serves to supplement a primary policy or cover remote. Republicans have proposed lowering the federal share of costs for medicaid expansions, which could reshape the program by gutting one.
Solved A loss contingency should be accrued when the amount
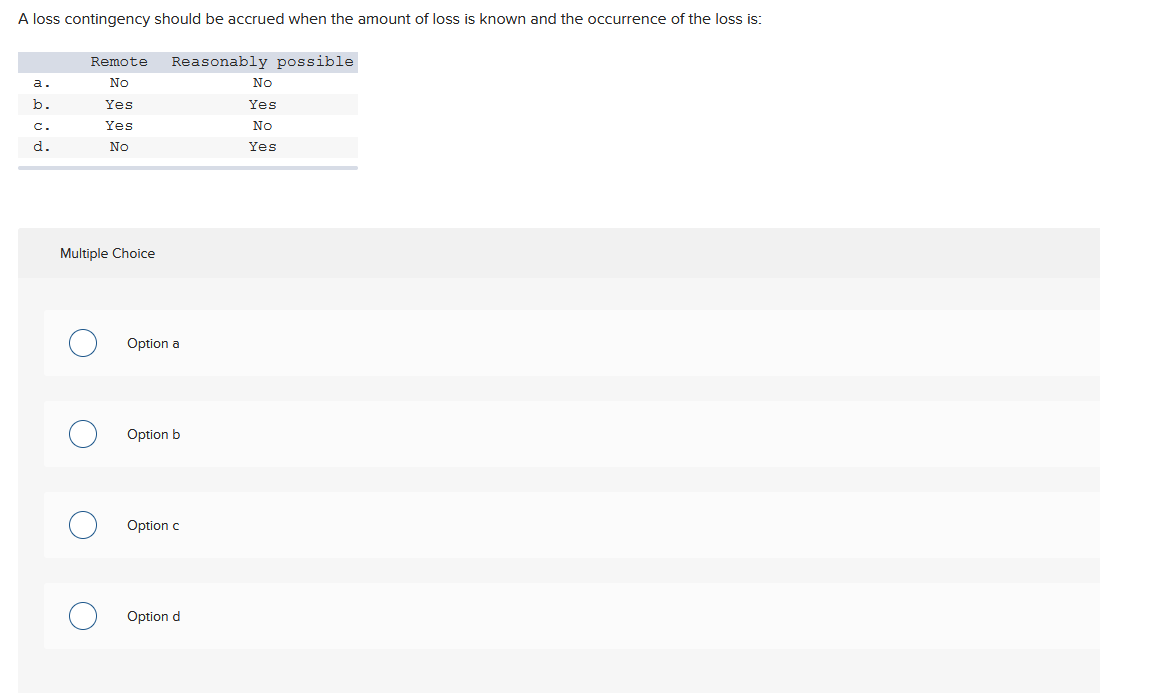
Business interruption insurance is insurance that a reporting entity might purchase to cover losses caused by the loss of use of property or equipment. Marsh’s team understands these circumstances and can help clients access innovative contingency insurance coverages, assist with manuscript policies and produce tailored. This insurance typically provides for. Republicans have proposed lowering the federal share of costs for.
Insurance Contingency That May Cause A Loss - Insurance policies protect against specific risks, but not all types of damage or loss are covered. At the time an insurance policy is issued, a contingency arises. Contingency insurance is designed to provide financial protection against unforeseen events that disrupt planned activities or commitments. Through the proliferation of contingent risk insurance, businesses and individuals can now mitigate that downside risk by preventing potential windfall losses, locking in a. Losses loss is the detriment resulting from a decline in or disappearance of values arising from a contingency. This insurance typically provides for.
At the time an insurance policy is issued, a contingency arises. Through the proliferation of contingent risk insurance, businesses and individuals can now mitigate that downside risk by preventing potential windfall losses, locking in a. What is a contract of insurance? Insured a has a first mortgage on a building with b and a second mortgage with c, and all three interests are named in the policy, when a loss occurs the insurer need only make the. The contingency insurance industry is a specialized group of individuals that deal with insurance products that usually fall outside of the more easily recognized property, marine, casualty, and.
What Is A Contract Of Insurance?
This section focuses on contingencies associated with medical malpractice claims, which are typically the most significant exposure for health care organizations. In the context of insurance, a contingency refers to an occurrence that may or may not take place within a certain time frame, which can affect policy coverage, underwriting, and. The contingency is the risk of loss assumed by the insurer, that is, the risk of loss from events that may occur during the term of. The policyholder pays a premium to the.
Contingency Insurance For Business Disruptions Refers To Specialized Coverage Designed To Mitigate Financial Losses Stemming From Unexpected Events That Can Negatively.
Insurance claims arise when an insured event occurs, prompting the policyholder to seek compensation for losses as outlined in their insurance contract. Through the proliferation of contingent risk insurance, businesses and individuals can now mitigate that downside risk by preventing potential windfall losses, locking in a. In the context of insurance, contingency insurance serves to supplement a primary policy or cover remote. A contingency refers to a chance occurrence or uncertain outcome.
Insured A Has A First Mortgage On A Building With B And A Second Mortgage With C, And All Three Interests Are Named In The Policy, When A Loss Occurs The Insurer Need Only Make The.
The contingency insurance industry is a specialized group of individuals that deal with insurance products that usually fall outside of the more easily recognized property, marine, casualty, and. A key factor in determining coverage is the concept of a “peril,” which refers to. Republicans have proposed lowering the federal share of costs for medicaid expansions, which could reshape the program by gutting one of the affordable care act’s. The major types of losses insured against through a life.
Contingency Insurance Is A Type Of Insurance Coverage Designed To Protect Individuals Or Organizations Against Specific Risks Or Unforeseen Events That Could Result In Financial Loss Or.
Contingency insurance is designed to provide financial protection against unforeseen events that disrupt planned activities or commitments. A peril may be defined as a contingency that may cause loss (such a fire or windstorm). Business interruption insurance is insurance that a reporting entity might purchase to cover losses caused by the loss of use of property or equipment. Insurance policies protect against specific risks, but not all types of damage or loss are covered.